
Techno Electric: Power and Digital Infra Play
With investors rushing to artificial intelligence software, semiconductor firms, and internet platforms, is one of India's most critical infrastructure shifts quietly happening in the background?
For years, investment has been focused on companies at the front end of technology shifts. AI, cloud services, digital applications, and software platforms have taken center stage. But these companies are just one piece of a much larger shift.
Every digital economy has a need for infrastructure. Data centers need power. Cloud computing needs connectivity. Smart cities need intelligent grids. Renewable energy needs transmission. AI infrastructure requires considerable electrical capacity before a server can even be plugged in.
As India goes through possibly its biggest infrastructure spending cycle ever, a different class of company is beginning to emerge: companies working in the back end, those that build the systems enabling the economy to run.
One company that appears to span a number of these themes is Techno Electric & Engineering Co Ltd (TEECL).
Many investors think of Techno Electric solely as a traditional EPC company with a focus on power projects. The business is likely more than that.
The company today has a footprint in power transmission, smart metering, digital substations, transmission assets, grid modernization, and, significantly, data center infrastructure. The company's long-term goal is to evolve away from traditional EPC services and become a power and digital infrastructure platform.
The differentiation is critical.
EPC firms design, build and leave the project.
Infrastructure platforms own the asset, and build businesses that derive ongoing revenue, riding long-term trends.
The shift is ongoing, but the foundation already exists. The business has 40 years of experience. It has completed more than 450 projects and it has domain expertise throughout India's power infrastructure.
The stock market is a device for transferring money from the impatient to the patient : Warren Buffett
At the same time, it is also deploying a lot of capital into data center and digital infrastructure projects which are beginning to take shape and can redefine the company's revenue profile over the next few years.
The success or failure of this shift will depend on management's execution, but there's little question it's working at the forefront of many important Indian infrastructure trends, a story that deserves further analysis.
The Business Model: Why Techno Electric Is No Longer Just an EPC Company
One of the largest investors errors is to judge a company by what it has been rather than what it is becoming. For many years Techno Electric was synonymous with Engineering, procurement and construction in power projects. It established its credentials in Transmission and Distribution and was a name known in India's power environment. That legacy business is still significant; but the company of today operates across a broader canvas.The company produces value in three broad business categories namely (EPC Services, Advanced Metering Infrastructure (AMI) & Data Centers) according to the company’s annual report. Every one of these categories reflects a different structural trend; while EPC business continues to facilitate power generation, transmission, sub-stations, grid infrastructure, FGD systems, and HVDC related work, AMI caters to smart metering infrastructure and grid digitization; data centers are established to tap into demand for digital infrastructure.
What is particularly interesting about this mix is the extent to which each of these business lines supports a different part of the modernization of India. The former relates to the building blocks of economic growth, the second to smart power grids and data centers to digitization. Thus rather than being subject to one cycle, the business is subject to several simultaneously. This diversity is visible not just in its business operations but also in its clientele.
The company provides solutions for:
• Thermal power facilities
• Renewable energy projects
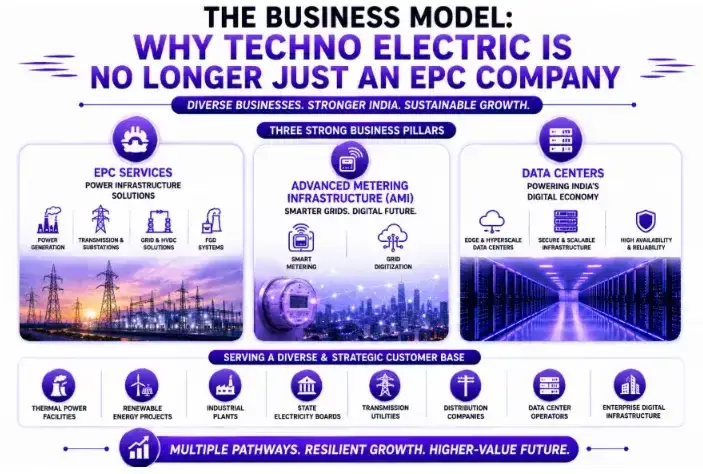
• Industrial plants
• State electricity boards
• Transmission utilities
• Distribution companies
• Data center operators
• Enterprise digital infrastructure projects
This breadth of exposure creates multiple avenues for growth.
If one segment slows temporarily, another can potentially provide support.
That flexibility often becomes particularly valuable during periods of economic uncertainty.
Perhaps more importantly, it creates a platform from which management can gradually move toward higher-value infrastructure opportunities.
And that appears to be exactly what is happening.
The Infrastructure Layer Most Investors Ignore
When investors talk about technological transformation, the discussions invariably turn to applications: AI, cloud computing, digital services and software platforms. It's easy to see why excitement surrounds these concepts, as they are quickly transforming economies and industries. Less widely discussed is the physical infrastructure needed for all of these things to work. What technology can do vs what technology needs to function.
Every AI algorithm will consume power. Every cloud application will require server space in a data center. Every digital transaction will require the continued functionality of an electrical network. These are not tertiary concerns; they are primary constraints. The world of modern applications can't function at scale without power infrastructure. There would be no digital infrastructure. While these considerations seem fairly obvious when highlighted, they're overlooked by most in favor of more exciting end-market trends and the resulting potential for sustainable investment.
This is where Techno Electric's situation gets interesting. A major expansion is taking place within India's power infrastructure framework, fueled by energy demand growth, a growing digital economy and increased focus on updating India's grid. This power expansion is immense and has ramifications that will affect numerous segments of the infrastructure value chain. In multiple areas management points to sustained long-term investment opportunities to take advantage of; an investor would need to consider not only what the company has done but also what it's well positioned to do.
• Renewable integration
• Grid modernization
• HVDC projects
• STATCOM deployments
• Battery storage infrastructure
• 765kV transmission systems
• Digital substations
These are not short-term trends.
Most of these projects require years of planning, significant capital investment and long execution cycles.
The company already possesses substantial experience within this ecosystem.
Management highlighted that Techno Electric has a legacy spanning approximately 45 years and has participated in projects associated with nearly half of India's national grid infrastructure.
That experience provides credibility in a sector where technical expertise, execution capability and customer relationships matter significantly.
The order book composition also reflects the company's positioning.
Transmission accounts for over half of the total order book, making it the single largest business segment.
This matters because transmission infrastructure may become one of the most critical components of India's energy transition.
Renewable energy cannot reach consumers without transmission networks.
Solar parks require evacuation infrastructure.
Wind projects require grid connectivity.
Industrial growth requires reliable electricity delivery.
As India targets substantial renewable energy expansion, the need for transmission infrastructure naturally increases.
Why Power Sector Stocks are Booming – Data & Trend Analysis
Management appears highly optimistic about this opportunity and repeatedly described transmission as a long-duration growth cycle rather than a temporary demand spike.
Top Power Sector Stocks in India for 2026
That optimism forms one of the central pillars supporting the company's future strategy.
The Data Center Opportunity: The Growth Engine Emerging Behind the Scenes.
Transmission is still the cornerstone, yet it seems like another opportunity is getting management’s attention. This might turn out to be the most significant strategic change happening within the company.
Every management slide mentioned that Techno Electric is becoming more of a digital infrastructure platform than just an EPC player. And at the core of this change is the data center business. Data centers have the capability to provide long-term infrastructure assets that can generate predictable recurring revenue stream, unlike traditional EPC work.
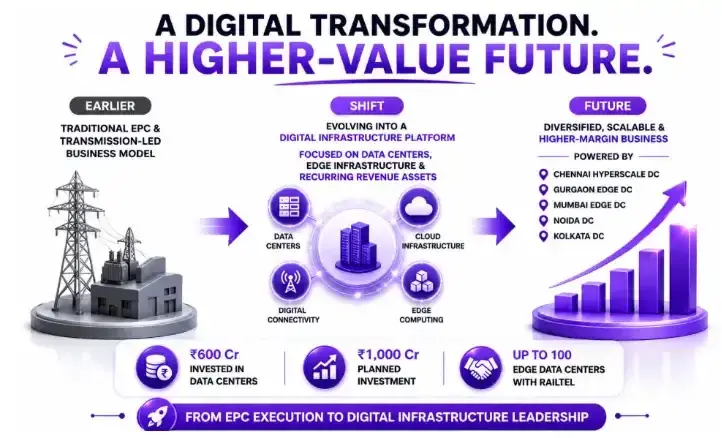
The company already has an evolving presence with multiple locations: Chennai Hyperscale Data Center, Gurgaon Edge Data Center, Mumbai Edge Data Center, Noida Data Center and Kolkata Data Center. Management mentioned that they have achieved positive progress with multiple projects and most of them have move from design phase to implementation phase. Gurgaon edge Data Center is already fully occupied; Mumbai is operational; Noida is going through the commissioning process and the company is getting strong interest from the customers and planning capacity expansion for the Chennai project. The management specifically pointed out that they have discussed capacity issues and future requirements with both domestic and global corporations.
What makes it so special is that they are entering at the right time; the country is expanding its digital infrastructure, cloud adoption is growing, businesses are increasing their digitalization pace, and the trend toward data localization is strong, leading to increase demand for state-of-the-art data center infrastructure.
The company already has a considerable amount invested into this segment; INR 600 crore has been spent into data centers, and the company has plan to further invest INR 1,000 crore in this segment. That kind of investment is a sign of long-term view and not a test case.
More interesting, possibly, is the relation with RailTel. Management stated that it has been given concession rights to build up to 100 edge data centers across tier-2 and tier-3 cities. If done successfully, this might turn out to be the company’s most diversified offering yet.
Company Transformation: From EPC Contractor to Infrastructure Platform
While investors might currently perceive Techno Electric simply as an EPC contractor, the most significant aspect of what is happening within the company is being overlooked. In numerous places throughout management'sFY26commentary, it was clear that its future involves far more than straightforward EPC execution. The recurring message is a transformation of Techno Electric from a "Pure EPC Company" to a "Digital Infrastructure Platform".On the surface, this might be considered simply a re-branding effort; however, in reality it represents a profound change to the company's economics. The economics of the traditional EPC business is a linear one – get a contract, complete a project, recognize revenue and repeat. Growth requires constant award of new EPC contracts. On the other hand, an infrastructure platform builds an asset base, has recurring revenue streams, captures structural demand trends and benefits from operating leverage as asset utilization grows.
It is likely that management is building these new, asset based, higher value-added revenue streams utilizing the cash flow being generated from their existing transmission and EPC operations. This can be clearly observed in all their various development efforts including Hyperscale Data Centers, Edge Data Centers, Smart Metering Assets, Digital Grid Infrastructure, Transmission Concessions through TBCB Projects.
Looked together, the initiative display a clear trend. The company is not moving away from EPC, it is using EPC as a stepping stone for a much higher value infrastructure asset base; it is one thing to have current revenue from an EPC project, it is another entirely to have long-duration earnings streams through the ownership of infrastructure assets.
While the process is ongoing, the destination is becoming clear. And investors typically only see these sorts of shifts after the financial reports catch up to the changes occurring within the business.
The big money is not in the buying or selling, but in the waiting.: Charlie Munger
Order Book: The Visibility Engine Behind Future Growth
Among the first items that an investor is likely to review with an infrastructure company is its order book. The reason is straightforward – an order book offers visibility on the future pipeline. It allows investors to grasp not only where a company has been but also where it is likely going. In the case of Techno Electric, the order book continues to be one of the strengths of the business.
For FY24, it stood at approximately ₹9,219 crore and was guided to be visible over the next three to five years. What is equally noteworthy is the breakdown of the order book, with transmission still dominating at 53.30% followed by distribution at 30.36%, generation at 14% and data centers at 2.34%. To the eye, this may suggest that the company has minimal order book in data centers; however, this observation may fail to capture the bigger picture.
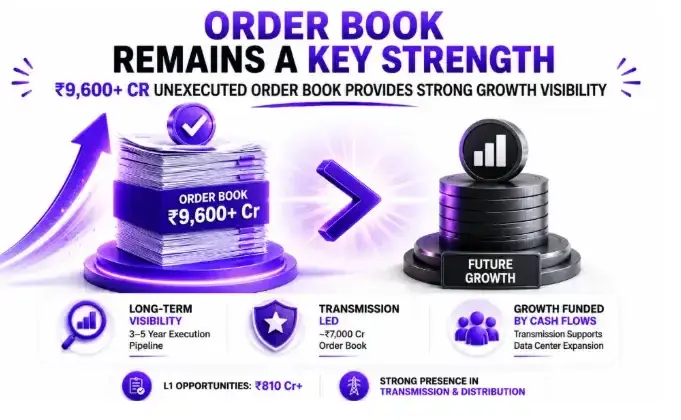
The transmission business is likely funding the company's foray into future growth avenues. Transmission business generates cash flows while data centers are a growth option and they complement each other. Management also shared that they were still actively involved in transmission bidding opportunities, were L1 on some major transmission opportunities of approximately ₹800 crore and were expecting a significant number of transmission award orders.
As of Q4 FY26, management indicated an unexecuted order book of approximately ₹9,600 crore plus new orders post-March and L1 opportunities of approximately ₹810 crore. Again, breakdown of this order book would still be transmission driven: ~₹7,000 crore (transmission), ~₹1,000 crore (FGD) and ~₹1,500 crore (AMI/distribution). What is relevant here is the fact that the transmission segment is the company's biggest earnings engine and though investor's interest may shift to data centers, the stability provided by the former is what finances the company's investment in the latter. This stability is quite strong.
In the short run, the market is a voting machine, but in the long run, it is a weighing machine: Benjamin Graham
Financial Performance: The Numbers Behind the Story
While narratives are nice, it comes down to how these strategies show up on the balance sheet. Luckily, on balance, the numbers seem to support the current strategy direction for Techno Electric.
For the FY24 numbers, the company posted a revenue of 1,680.8 million, an improvement over the prior year. EBITDA posted 222.6 million which represents more than 23% growth year-on-year, while the company's PAT stands at 269.7 million representing growth in PAT of more than 23%. EPS has grown over 25% to stand at 25.06. This shows not just the top line growth but also indicates growth in profitability.
More recently, the company performed strongly for FY26, too. The revenue posted an increase of 43.3% year-on-year to 3,251.6 million. EBITDA increased 36.1% year-on-year to 461.8 million, while the company's PAT stands at 4,487 million posting a 18.7% growth year-on-year. The figures reflect the continued growth in scale as well as profitability, despite the market dynamics.
However, not everything is smooth, and Q4 FY26 brings in some warning signals. While the company posted a revenue growth of approx 24% for Q4FY26, profitability came under pressure owing to higher operating costs, supply chain issues, increased logistics costs, increased input costs, increased energy inflation, and higher execution costs. This led to lower EBITDA margins, lower PAT margins, and negative PAT growth in the quarter.

This needs monitoring, and the most pertinent question for investors at this point is whether this represents a short-term, execution-driven problem, or a long-term issue in structural terms. In any case, the management remains upbeat that the larger trajectory for growth is continuing, and the full year numbers reflect this for the moment.
Despite being largely in the shadows as investors focus on the more exciting, albeit small, data centre business, another opportunity has steadily been developing. This is in Advanced Metering Infrastructure (AMI), which is increasingly gaining traction as the power sector undergoes a digital transformation, replacing old metering systems with smart metering systems, enabling better billing, reducing energy losses and real-time monitoring.
In the FY26 quarter, execution progress of AMI was significantly up with installation progress in states such as Madhya Pradesh showing an improvement from 86% to 98% while Jharkhand improved from 52% to 63%. J&K improved from 34% to 49% and Tripura improved from 31% to 75%. Execution of the project rose from 50% in Q3FY26 to 69% in Q4FY26, overall. The company also reported an order book of 2.5 million meters, of which about 70% is in execution phase with full execution to happen in FY27.
What makes the story even more interesting here is that the management has not been chasing every possible meter for fear of not just scale, but for profitability. The management said that it is looking for profitable execution for this vertical and believes it has a right to price for profitability as opposed to just winning orders based on volumes. The DISCOM risks are too high and margins have to be managed closely.
This strategy is likely to be important in the long term. You generally do not create shareholder value out of mere scale, but you do if you can create scale profitably.
One of the most interesting developments disclosed by management during FY26:This is in relation to digital substations.
Historically, substations have been primarily an infrastructure-type asset centered around transmission and distribution. The latest iteration of the substation, however, is the digital substation, a station with significantly greater monitoring, automation, operational efficiency, and intelligibility.
Techno Electric just won a project for four 132kV digital substations that the management characterized as one of India's largest digital substation projects. Why does that matter? Because upgrading the grid is critical. The integration of renewables means more variable power input into the grid; utilities need a smarter grid; transmission providers need more visibility; grid operators need real-time information. Digital substations provide many solutions to these issues.
Management appears to see this area as a crucial growth area going forward and as perhaps the next phase of India's grid upgrade cycle. Investors traditionally focus on more "tangible" aspects of the infrastructure like transmission lines. The addition of an "intelligence" layer to the grid may be just as significant down the line. And Techno Electric appears poised to be a participant in that transformation.
The Data Center Expansion Strategy: Building for the Next Decade, Not the Next Quarter
While transmission today appears to be Techno Electric’s bread-and-butter, data centers appear to be what the company believes will change the business over the next decade. One term that was consistently reiterated during every quarterly discussion throughout FY26: Data centers. Not transmission, not EPC, not smart metering. Data centers. When management continually mentioned customer conversations, capacity increases, commissioning dates, occupancy levels, and future expansions – the sheer concentration seems to indicate the company believes digital infrastructure will be a dominant pillar of its future growth.The Chennai Hyperscale Data Center is arguably the most direct illustration of this belief. While the facility commissioned, client induction occurred and management relayed to us more intense engagement levels with domestic and international cloud providers. By Q4, management mentioned that already space was being leased and discussions about additional capacity were actively ongoing. They seemed confident in a high level of capacity commissioning by FY27 being utilized.
Meanwhile, The Gurgaon Edge Data Center has already proven its concept. The facility has not only commissioned and fully subscribed but also started generating revenue, as management relayed that it achieved 100% utilization and proved the necessity for edge data centers at such key locations. Mumbai has also been kicked off from planning to execution, Noida is in commissioning and Kolkata is under construction while multiple sites are still under assessment.
Collectively, this demonstrates a company building a network, rather than one site. The former typically possess much greater value than the latter due to their extended reach and broadened customer and service offerings that result in greater leverage and expanded ability to cater to demand.
It also adds more intrigue to this prospect when management is funding investments before demand manifests to everyone, as companies within infrastructure businesses that establish capacity ahead of peak demand cycles typically receive significantly higher returns when demand levels rise to fill capacity, and management seems to be setting the company up to achieve just that.
The RailTel Partnership: The Opportunity Few Investors May Be Appreciating
Perhaps one of the most surprising revelations from the management commentary is regarding RailTel. While this seems to be just an infrastructure partnership at face value, it has the potential to become one of the company’s most critical strategic options. Management revealed concession rights for building up to 100 Edge Data Centers in tier-2 and tier-3 cities.
Think about what this truly means. In all our discussions regarding data centers, the major focus has been on the larger metropolitan cities like Mumbai, Chennai, Delhi, Bangalore etc. But in reality digital adoption is growing rapidly beyond these metros. Cloud applications for enterprises, government services, e-commerce, work-from-home and AI technologies all require computing power much closer to end-users. This is exactly what edge data centers offer, bringing the computing power from a couple of mega centers to many distributed locations where the need is.
The management has already finalized locations for growth, some of them being Indore, Lucknow, Chandigarh, Vizag and Prayagraj. Successful execution of this strategy will lead to Techno Electric gaining a unique position in the changing digital infrastructure space in India. Building of huge data centers are a given, but many are shy from attempting to build a distributed edge network in the developing cities.
The play is nascent and will hinge on execution, but the opportunity is potentially large and the management seems determined.
The Transmission Supercycle: The Cash-Generating Engine
The headlines might be grabbing the attention of data centers but what the business has been continuing to support the rest still continues to support everything: transmission. Management was extremely disciplined on their commentary in FY26 and are intensely bullish on transmission assets.The simple reason is that the Indian power system is becoming increasingly complicated. The buildout of renewable capacity, distributed generation, increasing electricity demand and grid modernization needs are all driving transmission needs. Management outlined several strategic priorities; renewable integration, HVDC deployment, STATCOMs, storage infrastructure, digital substations and 765kv transmission were among some.
It is imperative to note management doesn't seem to be involved with renewable power generation but rather what enables renewable power to reach users. This is a significant difference. Power generation itself could become cyclical but the infrastructure enabling power has a more durable long-term outlook irrespective of which generation method is eventually
1,680 winners. Solar requires transmission, wind requires transmission, thermal power requires transmission, hydro requires transmission. The thread that binds is the grid.
Techno Electric have been involved in building up knowledge base in this sphere for decades and this may soon grow to be of greater value as India increases its infrastructure going forward
Capital Allocation: Where Management Is Putting Its Money
One of the best ways of finding management's real focus isn't by listening to what they say - it's to see what they are willing to put their money into. Here, the message from Techno Electric is loud and clear. The management is willing to bet big money on future growth platforms.
In the last two years, approximately 1,250 crore has been invested in data centers, edge data centers, smart metering, transmission assets and infrastructure opportunities. About 600 crore has already been spent on data centers and plans for another 1,000 crore. About 500 crore has been invested in smart metering with future plans as well.
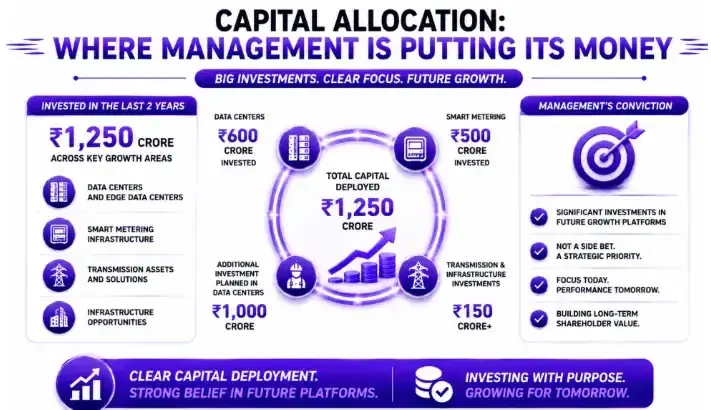
The implication for investors is that the management isn't treating data centers as a parallel business, or digital infrastructure as a trial run. It is obvious they consider it as strategically important. And what management's focus is upon often precedes its performance. Whether the strategy is a success only time will tell. However, the conviction level seems undeniable
If you double the number of experiments you do per year, you're going to double your inventiveness: Jeff Bezos
.
The Balance Sheet Advantage
It's easy to see opportunities in infrastructure, but that's meaningless if a company cannot finance it. That's where Techno Electric seemingly has a true advantage. Several balance sheet positives the company highlighted multiple times included a debt-free balance sheet, high liquidity, large cash & investments balances and prudent working capital management. The management indicated a cash and investments balance around 2,600 crore in FY26 and strong liquidity throughout the year with robust financial flexibility.
How to Read a Balance Sheet Like a Professional Investor
Why this is important: Infrastructure needs a long investment cycle. The facility is constructed before it becomes productive and becomes operational before it reaches a good utilization level. Companies with weak balance sheets will find it tough during these phases and thus must stop investing. With Techno Electric's balance sheet, management is enabled to make that investment. And optionality is valuable; it is especially valuable when several investment opportunities come into existence at roughly the same time.
Growth Drivers: Everything Appears to Be Moving in the Same Direction
What is most appealing about the Techno Electric story is that growth isn't a one driver story. Multiple drivers appear to be at play.
Power Transmission Expansion. The largest segment and biggest chunk of the order book remains Transmission. Demand still driven by renewable integration and grid modernization
Data Center Growth. Multiple data centers are in operation or in the process of construction/commissioning stage. Customer interaction and expansion opportunities reported by the management on a regular basis.
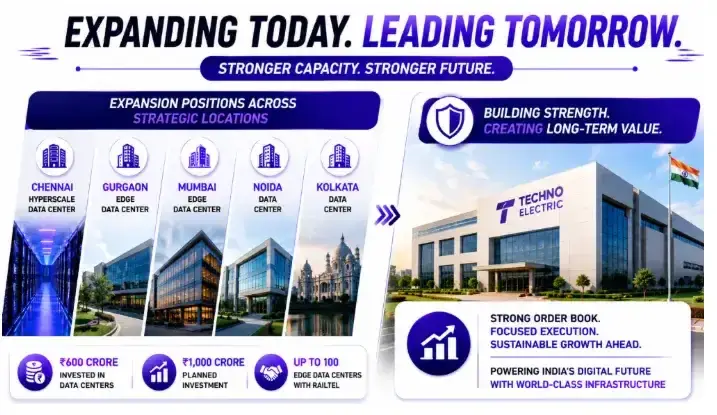
Edge Data Centers. RailTel deal provides access to a massive distributed data infrastructure across India
Smart Metering. Execution has been improving across projects, while a large volume of deployments still pending.
Digital Substations. Grid modernization leads to opportunities in new generation digital infrastructure.
TBCB Opportunities. Strong bid pipeline with meaningful wins expected highlighted by management.
Renewable Infrastructure. Indirectly leads to more transmission infrastructure and grid modernization and substations.
It is interesting to note that none of the above are in competition. They seem to reinforce each other, and the result is multiple pathways to growth
Risks Investors Should Monitor
No investment narrative can be complete without talking about the risks, and there are a couple that stand out for Techno Electric. The first is execution risk. The company has laid out grand plans, from data centers, smart metering to transmission assets and digital infrastructure, and execution will tell the ultimate story. Related is margin pressure, since revenue growth is not translating into profit growth, a fact evident in FY26. Cost inflation, logistics costs, procurement costs, all impacted margins in the year. The utilization risk of the data centers needs to be watched. A good sum of money has already been allocated, and future returns will depend on customer addition and usage build up. Likewise, smart metering will come with risks of its own, with the management already having acceptedDISCOM- related risks, and margin issues. The capital allocation risk cannot be ignored either. All the significant investments made needs to yield results. Project delay, as is common for any business engaged in the infrastructure space, with approval processes, construction timelines, customer addition and execution itself, also remain a persistent risk.
How to Reduce Risk and Stabilize Investment Returns
These risks require ongoing monitoring.

Explore our Products
Research Framework

Emerging Titans
Combination of quantitative analysis, industry tailwinds, and management assessment - SPRINT investment philosophy

Tiny Titans
Heavy emphasis on scuttlebutt research, plant visits, and early on-ground signals
Conclusion — Techno Electric in Brief
Techno Electric today looks very different than many may remember it as. Today what was considered as only a power sector EPC contractor, has been trying to reinvent itself as a power and digital infrastructure platform player. Transmission remains to be the backbone, providing most of the current earnings, while smart metering allows an opportunity in terms of visibility on execution. Digital substations is the next area of growth. While the company could leverage its strength in transmissions into more business opportunities in the power sector, we feel the more exciting long term theme for Techno Electric is the foray into data centers. The management is making aggressive investment in hyperscale facilities and edge infra, and developing digital platforms while simultaneously continuing the large and cash generative transmission business which is enabling future growth. Balance sheet is robust, the order book continues to be sizeable, and seems to be playing multiple themes at the same time. However, the journey is still far from complete, and perhaps, just getting started in many ways. The next few years would reveal if Techno Electric is truly moving towards being a long term infrastructure company in the power and digital sector or it continues to be perceived as only a trusted EPC player. While the opportunity is evident and money is deployed, the execution would be key.
How to Analyze a Mid-Cap Company – A Complete, Practical Framework
FAQs
Q1. So what is Techno Electric doing today?
+Techno Electric operates in 3 different segments, that are EPC Services, Advanced Metering Infrastructure and Data centers. In the past known as transmission and power infrastructure development business and more recently adding digital infrastructure and recurring revenue based business.
Q2. Why has management focused so heavily on data centers?
+Management is quite convinced that this is where major future growth would come from. Several facilities are operational or being set up and they have already deployed huge amount of capital into these developments. Data center development has potential for recurring revenue generation in comparison to one-off revenue from EPC contracts.
Q3. How significant is the RailTel partnership?
+The RailTel partnership has a concession which provides potential development of upto 100 edge data centers across tier-2 and tier-3 cities of India. This could turn out to be a differentiating distributed digital infrastructure.
Q4. What is the current business of Techno Electric?
+Transmission infrastructure still continues to be the biggest in the order book and is the current cash cow of the company.
Q5. What should investors watch in the next 12-24 months?
+Data center utilization, new transmission orders, smart meter execution, margin recovery and capital allocation are factors which will determine the performance over next few quarters. The crucial question will be how successful management's ambitious plans to grow digitally infrastructure are in actual revenue generation.

High growth stock specialist, Value Educator
Shashank Mahajan is an equity research professional with over 12 years of experience in identifying high-potential SME and micro-cap stocks at an early stage. He follows a rigorous scuttlebutt research–driven approach, combining on-ground insights with deep financial analysis. Shashank specializes in uncovering under-researched and under-owned companies with strong management quality and long-term growth potential. Through disciplined research and early identification, he focuses on spotting tomorrow’s market leaders before they enter the mainstream investor radar.

Zen Technologies: Why Revenue Fell After Its Biggest Win

Data Patterns: India's Radar Designer and Its Waiting Orders

KSH International: The Wire Inside India's Transformers

Krishna Defence: The Steel Behind India's Warship Hulls

PNG Jewellers: A 194-Year-Old Name Goes National

Axiscades: From Services to Missile and Radar Electronics
Explore our Products
Research Framework
Emerging Titans
Combination of quantitative analysis, industry tailwinds, and management assessment - SPRINT investment philosophy
Tiny Titans
Heavy emphasis on scuttlebutt research, plant visits, and early on-ground signals


 Orders
 Subscription
 Share with friends
 Logout


Required Details
₹23999.00
(12 month subscription)
As per SEBI regulations, all users are mandated to complete the KYC that is validated for 1 year. Post payment, you will be redirected to the KYC screen


No comments yet. Be the first to comment!