
TD Power Systems: Riding India's Capex Cycle
The economy of India has been consistently strong during an unsettled world. The real GDP of India showed an 8.2 percent growth rate for its most recent quarter indicating that India is solidly performing. The economy of India is forecasted to exhibit approximately 6.8 percent growth for the full calendar year.

India's capital expenditure cycle is clearly on solid footing and has become wider and more sustainable than before. Under various initiatives such as the national infrastructure pipeline and Make in India, investments are occurring in the Indian infrastructure, defense, power, and manufacturing sectors. The most notable is the return of private sector investment complementing government investment; this combination is driving exceptional industrial equipment demand for companies like TD Power Systems Limited.
As well, the growth of power consumption in India continues to increase yearly. Growing incomes, urbanization, data centers, and electrification trends are driving power demand higher each year. The Central Electricity Authority forecasts that this trend will remain for several years. As a result, there is increasing and long-term demand for electricity equipment manufacturers such as TD Power Systems Limited.

TD Power Systems Limited's niche positioning within the industrial power equipment sector has created tremendous opportunity for the company. As industries around the world increase both capacity and power demand, the need for reliable generators and motors will become critical in all sectors including cement, steel and renewables. There is also an opportunity for TD Power to take advantage of growing export markets (especially with continued demand for efficient, cost-competitive equipment) which, combined with domestic capital expenditure, will provide a long runway for the company’s growth.
“Opportunities come infrequently. When it rains gold, put out the bucket, not the thimble.” — Warren Buffett.
With India entering a powerful capex and energy demand cycle, companies aligned with this trend are naturally coming into focus. Let’s dive in and understand TD Power Systems Limited, and see how it fits into this larger structural growth story.
Business Positioning & Product Strength
TD Power Systems Limited operates in a highly specialized segment of industrial power equipment, where customization is not optional but essential. Its ability to design generators and motors based on precise customer requirements creates a strong competitive moat. This is not a commoditized product business, which naturally supports better pricing power and long-term relationships.
The company has created an extensive range of products that are diversified at a strategic level, with thermal, hydroelectric, diesel, gas and renewable energy applications into the generator set power range from 1 to 200 MW or to 250 MVA for both mid-range and large-scale industrial needs. Having the ability to provide products for so many different applications ensures that customer demand will not be concentrated entirely within one industry/segment.
What makes this positioning different from most competitors is not only its relationship with the power value chain but also its continued relevance to captive power plants, renewable energy generation and power grid applications. This ensures structural rather than cyclical demand for TD Power's products.
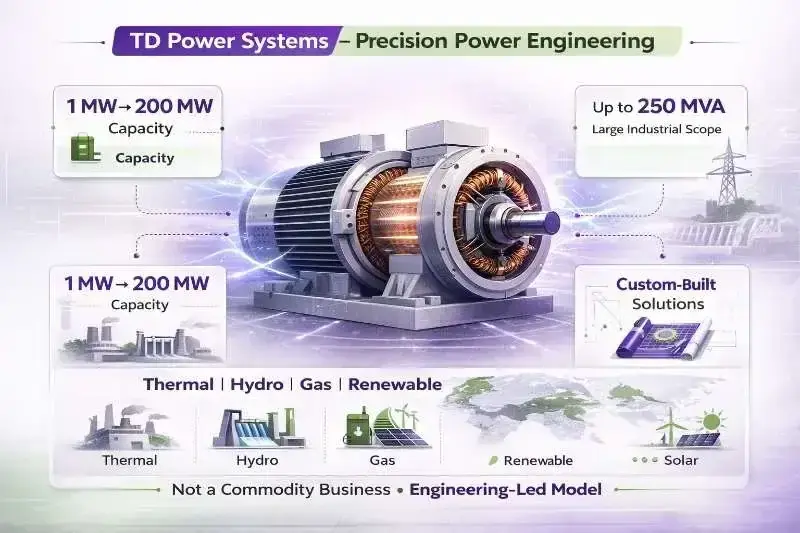
Another fundamental advantage is the company's engineering driven approach where customized, rather than standard, solutions are developed. This results in higher switching costs for customers when they want to replace equipment as the replacement process is often technically complex and has operational risk; creating long-term client stickiness.
Curious to learn more about mid-cap companies? Read our article: How to Analyze a Mid-Cap Company – A Complete, Practical Framework
Additionally, the company's credibility has been established within the global original equipment manufacturing (OEM) world; this is something very few companies have achieved in this industry space. As a result of this credibility, TD Power will continue to have predictable demand for its products and access to global markets. This is a subtle, but very real competitive advantage.
It is possible for TD Power to operate on multiple fuels therefore allowing it to be future ready since it does not focus on only one technology or type of fuel. Furthermore, having this flexibility leads to a more sustainable future for the entire company.
Ultimately, TD Power represents a convergence point in terms of growth in industry and demand for energy. Therefore, durable business models are usually located at these types of intersections. For investors, this type of location represents a long runway or period of time for growth.
Order Book Strength & Growth Visibility
One of the clearest indicators of future growth is the order book, and TD Power’s numbers are hard to ignore. With an order book of around ₹18,450 crore, the company has strong revenue visibility for multiple quarters ahead. This significantly reduces earnings uncertainty.
The core manufacturing segment of TD Power represents ₹15,600 crore of their total order book indicating that this portion of the company's business is strong. In addition, the diversification within the railways and other segments create balance without detracting from the core of TD's business.
What stands out even more is the pace of backlog expansion. Pending orders have grown 54% YoY and more than doubled over the past two years. This is not just steady growth, but a clear acceleration in demand.
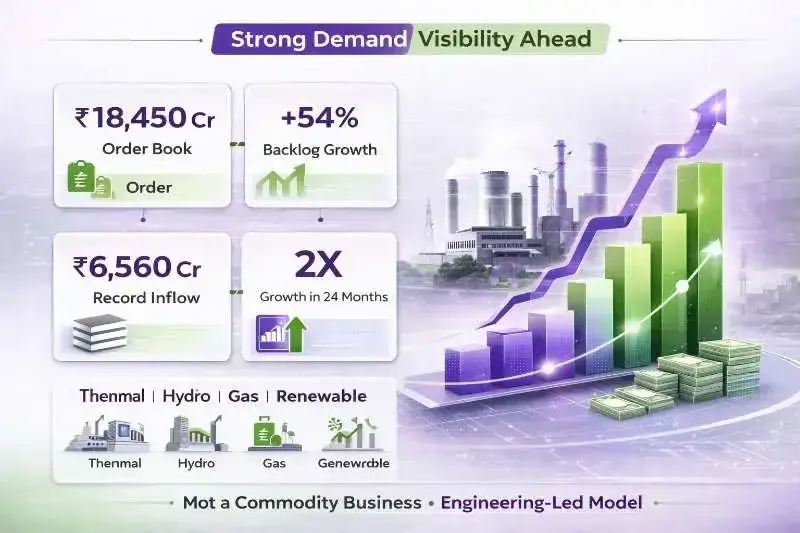
Order inflow for Q3 was ₹6,560 crore, representing an all-time high for TD Power. Furthermore, the 61% growth in YoY indicates that the demand is extremely strong and increasing at a fast pace which is supportive of a positive business cycle.
Such high volume orders are also indicative that customers are making commitments to long-term capacity investment which fits into the broader capital expenditure (capex) cycle that is being experienced across all industries. This is not a short-term spike in order volume, but rather part of a larger trend.
Another important factor is the quality of orders. A higher share of large and export-oriented orders typically supports better margins and execution efficiency. This adds depth to the growth story.
If you are interested in knowing about penny stocks and understanding how they work, then read our article: What are penny stocks? The complete beginner's guide: pros & cons
The growing order book also acts as a buffer during uncertain periods. Even if new orders slow down temporarily, execution of existing orders can sustain revenue growth. This improves resilience.
For investors, strong order visibility combined with rising inflows is often a sign of a business entering a powerful growth phase. TD Power seems to be in that zone.
Financial Performance & Margin Profile
The company's financial capabilities demonstrate how sturdy the foundation of its business is. For instance, standalone sales increased 32% from year-ago levels to ₹1,194 crores, while income after tax (PAT) rose 41% to ₹154 crores, signifying significant operating leverage.
Despite difficulties with supplier pricing due to rising commodity prices, margins have performed well. In particular, EBITDA margin increased to 18.3%, which indicates the company has both pricing power and expense restraint, neither of which can be easily controlled in a manufacturing business.
According to the company's management, they believe they can maintain their gross margins at approximately 35%. Therefore, any price inflation resulting from increasing copper costs may be passed on to customers. This suggests a strong position in the market.
Additionally, the company has a substantial cash position of ₹193 crores. This enhances the company's overall financial standing and allows for additional capital investments, as well as decreases its overall financial risk.
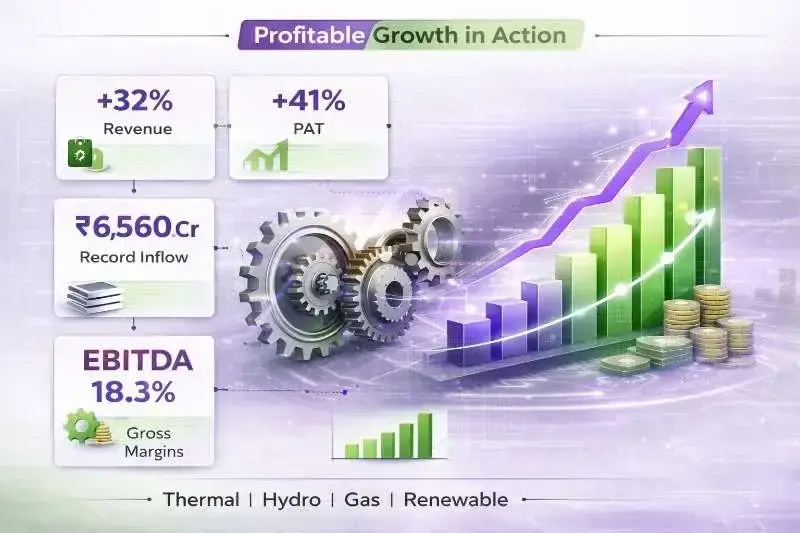
Operating leverage is clearly visible, as profit growth is outpacing revenue growth. As volumes increase, fixed costs get spread over a larger base. This naturally boosts profitability.
Curious about what market cap actually means when it comes to stocks? Read our article on: What is Market Capitalization? Large, Mid, Small Cap Explained with Examples
Another interesting aspect is the company’s ability to maintain margins across product segments. This indicates a balanced portfolio without overdependence on a single high-margin product. It adds stability.
Even with rising input costs, the company has managed to protect profitability. This shows disciplined execution and effective pricing strategies. Such consistency builds investor confidence.
Overall, the financial profile reflects a company that is not just growing, but doing so in a sustainable and profitable manner. This is a key trait of quality businesses.
Export Engine & Global Opportunity
Exports have become the primary growth driver for TD Power, and the numbers clearly reflect this trend. Around 75–80% of the order mix is export-driven, significantly expanding the company’s addressable market. This reduces dependence on domestic demand cycles.
Q3 was a major quarter. Order inflow was primarily from outside of the US - 84%. This demonstrates that the Company has some very good global competitiveness. The Company is not only participating but is also getting a share of global markets.
For the first 9 months of the fiscal year, export inflows have grown 62% vs. last year. So there is continued momentum with export inflows. Such strong growth typically indicates good acceptance of products and capability to execute. This is also indicative of continued worldwide demand for the Company’s products.
The Company's relationships with approximately 45 global OEMs provide access to many different geographies and many different product applications. These relationships take many years to develop and represent an extremely high barrier to entry for competitors in the global marketplace.
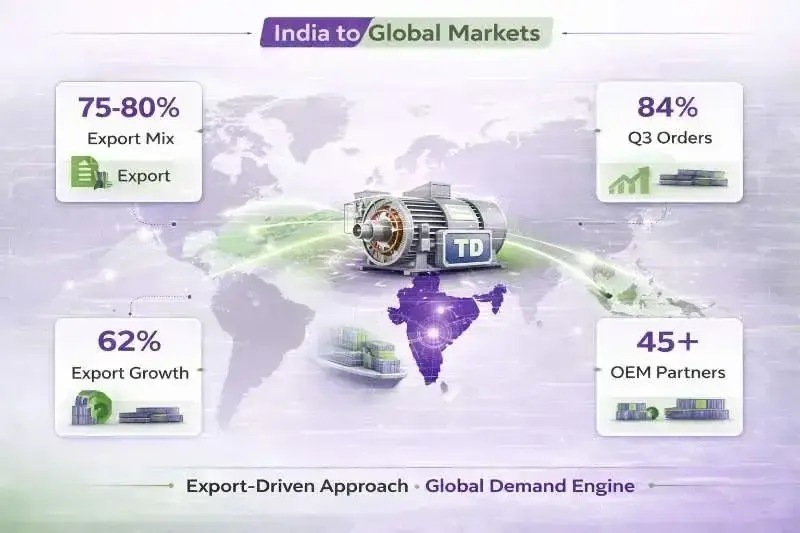
Export-led growth also offers diversification benefits. If one geography slows down, others can support overall performance. This reduces business volatility.
Currency movements further support export-oriented companies. A weaker rupee can improve realizations and margins. TD Power is well positioned to benefit from such trends.
The company has also reduced hedging to around 10%, reflecting confidence in favorable forex movements. This could enhance profitability in the near term. However, it also introduces some volatility.
Overall, exports are not just a growth driver but a structural pillar of the business. This global orientation significantly strengthens the long-term investment case.
Capacity Expansion & Execution Capability
Capacity expansion is essential for long-term manufacturing growth, and TD Power appears to execute on this efficiently. The launch of Plant 3 is a key milestone in the company’s expansion journey and also sets the stage for future growth.
Prior to the new plant being operational, the company had been generating about ₹450 crore of revenue each quarter, demonstrating its existing capacity utilization and strong demand.
With Plant 3 now operational, the company expects to achieve revenue of ₹550–600 crore on a quarterly basis, which significantly expands potential revenue growth and increases scalability.
What stands out is the company’s disciplined approach to capital allocation. The company has no significant plans to add new capacity until FY28, indicating an intent to focus on optimally utilizing its current assets.
By taking this approach, the company minimizes the risk of overcapacity during a cycle downturn and also maximizes return on capital employed. Companies generally mature in their approach to capital allocation over time.
The company incurred some short-term costs during the ramp-up of Plant 3, such as personnel and machinery relocation, which should normalize over time. As utilization increases, the company’s margins will also increase.
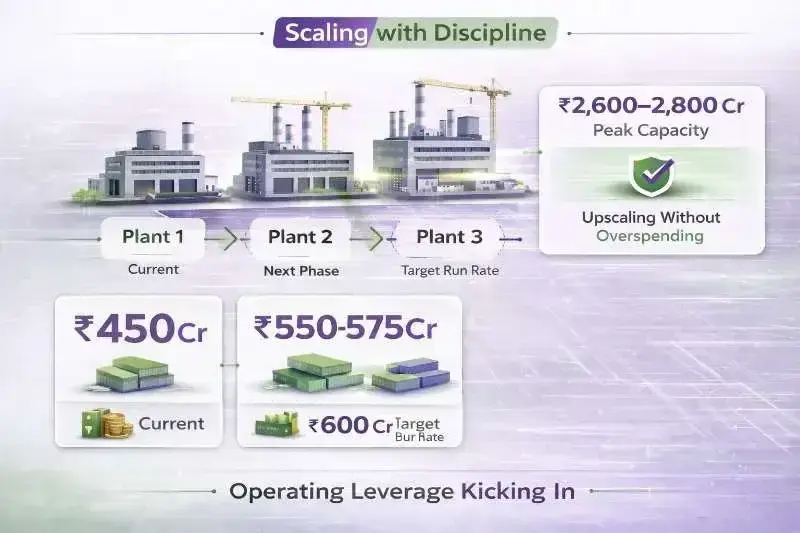
Increased operating leverage will be a key driver of profitability for the company as production increases and fixed costs are absorbed more efficiently.
Execution remains the key, and so far, the company has demonstrated consistency. If it continues on this path, the benefits of capacity expansion could be significant.
Segment Tailwinds & Future Growth Drivers
The strongest growth driver for TD Power is the gas turbine and gas engine segment. This segment is benefiting from rising demand for captive power, especially from data centers. It represents a structural opportunity.
Curious to find what debt signifies for a company and how it can impact your long-term returns? Read our article: What is Debt to Equity Ratio? Why it Matters for Small Cap Investing.
Management has indicated strong visibility in this segment till 2030. This suggests that the growth is not short-lived but part of a long-term trend. Such visibility is rare in cyclical industries.
Explore our Products
Research Framework

Emerging Titans
Combination of quantitative analysis, industry tailwinds, and management assessment - SPRINT investment philosophy

Tiny Titans
Heavy emphasis on scuttlebutt research, plant visits, and early on-ground signals
Another emerging opportunity is grid stabilization and related applications. As renewable energy penetration increases, such solutions become critical. This adds a new dimension to demand.
Hydro is also gaining traction, particularly in refurbishment projects. The company expects its highest-ever performance in this segment next year. This is a significant development.
Refurbishment offers steady demand as it is less dependent on new project cycles. It also provides recurring opportunities. This adds stability to the business model.
Steam turbines continue to grow at a steady pace of 10–12%. This provides a stable base and balances high-growth segments. Such balance is important for consistency.
The motors segment, while smaller, contributes incremental growth. Even a 10–15% growth rate adds to overall stability. It also diversifies revenue streams.
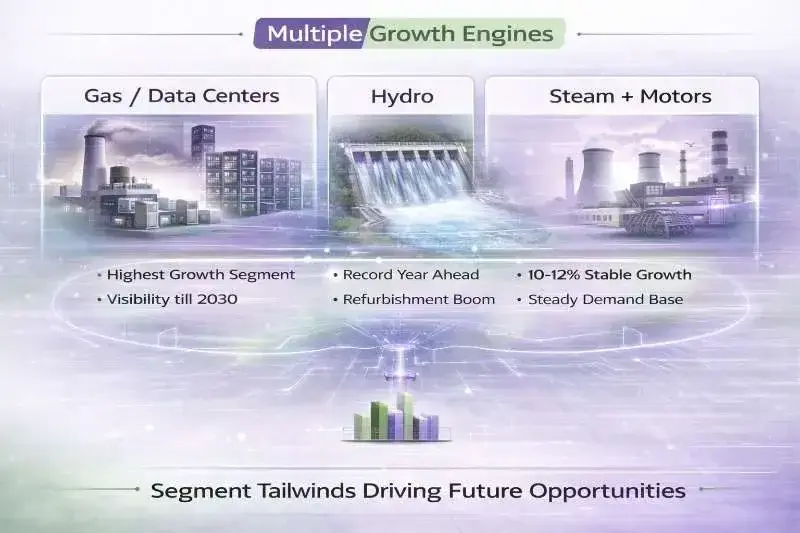
Overall, the company benefits from multiple growth drivers across segments. This reduces dependence on any single factor. It strengthens long-term growth visibility.
Conclusion & Investment View
“Big money is not in the buying and selling, but in the waiting.” — Charlie Munger. TD Power appears to be at a point where multiple growth drivers are aligning simultaneously. This is often where strong investment stories begin.
Growth will be supported by order books (backlogs), export activity, and increased capacity (increased production volume). Visibility is becoming better.
A good amount of this growth will be driven by exports and demand for data centre requirements and gas-based power. Each of these events is structural in nature and will sustain growth for a longer period. Thus, there will be greater certainty.
Additionally, risks have been included: commodity price fluctuations with copper prices being one; but the forex rates (or currency exchange rates) may follow different patterns due to low to no foreign exchange hedging (not all revenue from sales is hedged for exchange effect). The global demand cycle for the products also needs to be monitored.
Competition from international players and pricing pressure (and competition) in international markets will also create risks. Execution will continue to be the most important differentiator. Consistency will continue to be important.
Overall, TD Power Systems has a strong structural investment story due to alignment of 3 important components: growth, profitability and exposure to global markets. Each of these areas is compelling in combination with the other two. However, performance is likely to be highly dependent on valuation and timing.
Investors may want to consider a strategy that includes tracking the company closely and taking positions following corrections. Chasing performance is often an unsuccessful strategy over time. Patience will continue to provide an advantage.
If this breakdown helped you understand the industrial power equipment space and, more importantly, the story behind TD Power Systems Limited, then comment “POWER” below. If this analysis gave you a fresh perspective, share it with someone exploring equity research, and tell us which part of the business you found most interesting.
FAQs
Is TD Power Systems a direct play on India’s capex cycle?
+Yes, in many ways it is. As industries expand and new projects come up, demand for generators and industrial equipment naturally rises. TD Power sits right in this supply chain, benefiting whenever companies invest in capacity. This makes it closely linked to the broader capex revival.
What makes TD Power different from other power equipment companies?
+The company focuses on niche, high-efficiency generators rather than commoditized products. This allows better margins and pricing power compared to standard equipment players. Over time, this positioning helps it avoid pure price competition and build a stronger moat.
How does rising power demand impact TD Power’s growth?
+Higher power consumption means more capacity addition across thermal, hydro, and gas-based plants. Each new plant or upgrade needs generators and supporting equipment. This creates a steady pipeline of opportunities for TD Power across multiple segments.
Can exports be a meaningful growth driver for TD Power?
+Yes, exports are an important piece of the story. The company already supplies to global markets, which diversifies revenue beyond India. As global demand for efficient power equipment rises, exports can act as a strong growth lever.
Is TD Power a cyclical or long-term structural story?
+It is a mix of both. In the short term, performance can depend on order inflows and capex cycles. But structurally, rising electrification, industrial growth, and global energy needs provide a long-term runway for the business.

High growth stock specialist, Value Educator
Shashank Mahajan is an equity research professional with over 12 years of experience in identifying high-potential SME and micro-cap stocks at an early stage. He follows a rigorous scuttlebutt research–driven approach, combining on-ground insights with deep financial analysis. Shashank specializes in uncovering under-researched and under-owned companies with strong management quality and long-term growth potential. Through disciplined research and early identification, he focuses on spotting tomorrow’s market leaders before they enter the mainstream investor radar.

Glenmark: The USD 700 Mn Cancer Deal and Its Brands

Pharma Stocks in India 2026: Generics, APIs and CDMOs

Granules India: From Paracetamol to a 65% Gross Margin

Natco Pharma: After Revlimid, 29 Patent Challenges

Shilpa Medicare: Cancer APIs, Films and Biosimilars

Alembic Pharma: US Plants Pay Back, Margin Hits 22.2%
Explore our Products
Research Framework
Emerging Titans
Combination of quantitative analysis, industry tailwinds, and management assessment - SPRINT investment philosophy
Tiny Titans
Heavy emphasis on scuttlebutt research, plant visits, and early on-ground signals



Modern Warfare to Multibaggers
Key Trends. Strategic Shifts. Opportunities Ahead.
Today at 7:00 PM IST. Room opens 30 minutes before.
Don't Miss This Exclusive Webinar!
Join Value Educator to decode the key trends shaping India's defence sector and learn how to identify tomorrow's potential leaders in the space.
- In-depth research on India's defence sector
- Live Q&A session
- Actionable takeaways for long-term investors

 Orders
 Subscription
 Share with friends


Required Details
₹23999.00
(12 month subscription)
As per SEBI regulations, all users are mandated to complete the KYC that is validated for 1 year. Post payment, you will be redirected to the KYC screen


No comments yet. Be the first to comment!