
Inflation: The Silent Destroyer of Wealth

It used to be easy to find the same chocolate bar or snack at the local shop for ₹10, but in recent years, many people have realized that this is no longer the case.
Many people are now paying more for certain items; they’re also receiving smaller portions of some of the same items. At first glance, these changes seem insignificant; however, they begin to contribute to rising costs of groceries, increasing prices of fuel, etc. and soon we run out of money much quicker than we used to.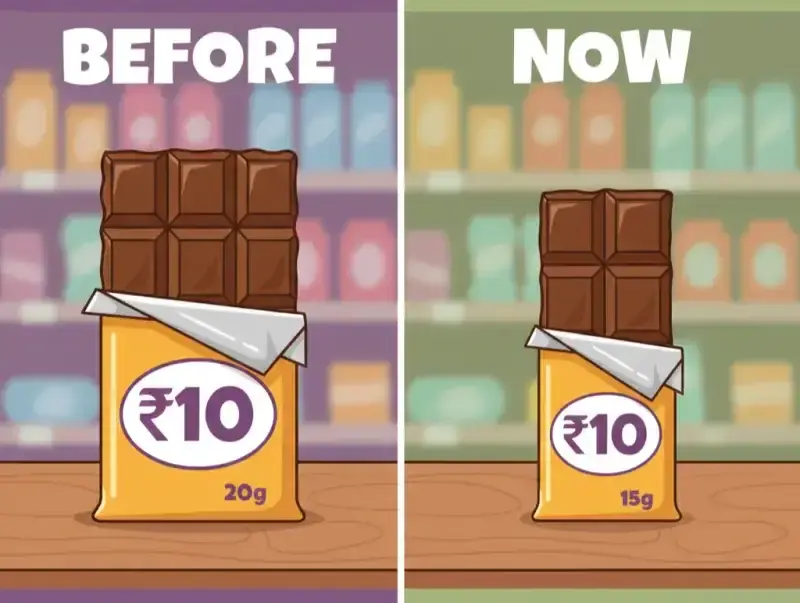
Nothing out of the ordinary has occurred overnight, but something definitely feels different; money doesn’t go as far as it used to.
This moment of realization is crucial for investors.Growth in finances is normally measured by higher wages, higher investment portfolios, or higher savings account balances. But in situations where inflation is constantly affecting the value of money, such figures may not necessarily be a reflection of growth.
Understanding the dynamics of inflation and how different sectors are affected by rising prices becomes an essential part of the learning process for anyone who wishes to protect and grow their actual wealth.
Inflation: The Hidden Force Behind Rising Prices
Inflation can be defined as the constant rise in the price level of goods and services. Although prices seem like a natural phenomenon in our day-to-day lives, it is only when we take into account the purchasing power of money that we are able to grasp the true significance of prices. As prices increase, the same amount of money will have less and less purchasing power.
This is why the difference between nominal and real value is important. Nominal value is simply the number we see on paper, such as a raise in salary or positive investment returns. Real value, on the other hand, is the actual value of money after taking into consideration the rising prices. In other words, financial growth is not only about making more money but also about maintaining the same amount of purchasing power.
“The biggest risk of inflation is not rising prices, it’s losing purchasing power.”- Ray Dalio
Inflation rarely occurs for a single reason. Inflation tends to build gradually through a mix of everyday pressures. When there are more buyers for a product than there are available, the prices are bound to rise. Companies can also increase the prices of their products if they have to pay more for their operations, such as if they have to pay more for labor, or if the cost of raw materials and transport costs rise. Apart from these considerations, the economic environment influences the intensity of inflation.
When Saving Isn’t Enough: How Inflation Quietly Eats Into Your Money
Saving money feels reassuring. Watching your bank balance grow or seeing a fixed deposit mature with interest gives a sense of progress, as if your financial future is moving in the right direction. However, inflation causes us to think about these figures differently. The key question is not only whether your money is growing but also whether it is growing at a rate that is at least keeping pace with the rising cost of living.
“Inflation is taxation without legislation.”- Milton Friedman
It is at this point that the concept of nominal versus real returns comes into play. Nominal returns are simply the figures, such as a fixed deposit rate of 5% or an investment that is growing positively. Real returns, on the other hand, paint a different picture altogether. They take into account inflation and ask a more practical question: "After prices have gone up, what can your money actually buy?"
Imagine earning 5% on a fixed deposit while inflation is running at 6%. On paper, your savings have increased. The truth is, your purchasing power has actually gone down slightly. You may not notice it at first, but believe me, it will show up in many different ways, such as when the price of groceries goes up, the price of gas becomes expensive, or the cost of living becomes higher even when your income is higher.
This is known as a negative real return. It does not feel like a loss because the numbers in your account are still going up, but the actual value of that money is quietly being left behind by inflation. Savings accounts and fixed deposits, which are commonly selected for their safety and predictable nature, may face a problem during such periods since their returns may not always be in line with the increasing prices.
Moving beyond traditional savings, however, requires understanding your own comfort with volatility and risk. Read More in our article: Understanding Risk vs. Reward: How to Gauge Your Risk Appetite
The impact of this in the long run can be better understood by analyzing the impact of compounding. Just as your investments earn interest through compounding, inflation also compounds, and this means that it steadily reduces the value of what your money can buy. For example, if you save ₹1 lakh today, it may show up as ₹1.3 lakh in a few years due to interest, but if the inflation rate has gone up over the years, then the value that it can buy may be less than the original ₹1 lakh.
This is why the effect of inflation is not only about rising prices; it is about realizing whether your savings are actually protecting value or losing it. This is also where understanding asset allocation becomes critical, because how you divide money between cash, equities, and other assets can determine whether your portfolio keeps up with inflation over time. Understand More through our article: Asset Allocation 101: The Key to Reducing Risk and Smoothing Returns
The impact of inflation on personal savings raises an even bigger issue for investors: if prices are rising and eroding the value of their money without them noticing, what is happening to businesses and the stock market as inflation begins to increase?
How Rising Prices Affect the Stock Market
Not all companies are affected by inflation. As inflation spreads through the economy, firms must navigate a new landscape of challenges and opportunities that shape their performance and, ultimately, their stock market behavior.
“Stocks are claims on real assets. In the long run, they tend to protect against inflation.” - Jeremy Siegel
The most extreme shift likely to happen is within revenue as well as expenses. For instance, some firms will likely increase their prices due to rising inflation. Companies having a strong brand, essential products, or loyal customers will find increasing their pricing much easier than those without. In these cases, revenue can increase simultaneously with inflation.
Other firms will find themselves operating in an increasingly tough environment. Inflation can result in the prices of inputs, such as raw materials, energy, labor, and logistics, increasing. This could make it more difficult for a firm to maintain its profit margin if it is unable to increase its prices. For example, there are companies in a commodity-based industry that will experience difficulty establishing or maintaining profitability when they see rapid increases in their own input costs.
The rate of inflation also affects the nature of market reactions. In situations where the rate of inflation is moderate, corporations tend to react gradually, and markets tend to remain stable. However, in cases where the rate of inflation rises sharply, central banks tend to respond by increasing interest rates in order to control inflation. Interest rates rise, making it harder for businesses to find capital, plus investors change how they appraise future income, creating shifts in stock prices across markets.
Read More : How to Read a Profit & Loss Statement (P&L) in 10 Minutes: A Practical Investor’s Guide
Additionally, inflation affects various sectors in different ways; some benefit from inflation while others suffer due to higher operating costs or demand. This aspect becomes a critical factor that explains why stock market reactions can be quite different during periods of inflation, and this becomes evident when we examine the situation at the sector level.
Whereas inflation influences the broader market environment, its actual effects are better understood when we examine the way in which various sectors react to it. Not all sectors are affected equally by rising prices, as some may find it easier to cope with the challenges than others.
Inflation and the Stock Market: Why Some Businesses Adapt While Others Struggle
Inflation does not automatically favour or harm specific industries. On the flip side, the response of the organization is dependent on several factors, such as its pricing ability, cost structure, and finances. As we look into how the three parts of the business operate, we can see why there are certain industries that can endure inflation better than other industries.
This is precisely why diversification matters; relying on a single sector during inflation can increase risk. Read More: Portfolio Diversification- How Many Stocks Should You Hold?
“It’s far better to buy a wonderful company at a fair price than a fair company at a wonderful price.”- Warren Buffett
Characteristics That May Support Resilience During Inflation
- Pricing Power
One of the most powerful benefits that can be realized during an inflationary period is the fact that companies can raise prices without necessarily impacting demand. This is because companies with strong brands or products that are considered essential will often raise prices incrementally as costs escalate. Consumer staples and FMCG companies are some of the best examples of such businesses. - Direct Link to Rising Commodity Prices
Those companies that are associated with commodities such as oil, gas, or metals may benefit if inflation is driven by the increasing price of commodities. Those companies that produce gas or mine commodities may see their revenues rise along with the rise in commodity prices. - Benefit from Interest Rate Changes
Financial institutions may have different experiences during interest rate cycles that are driven by inflation. For instance, some financial institutions may benefit from the increase in lending spreads when interest rates increase. - Exposure to Real Assets
Industries tied to physical assets, including infrastructure or certain real estate segments, are sometimes viewed as more adaptable because asset values may rise along with inflation.
Characteristics That May Create Vulnerability During Inflation
- Limited Pricing Power
Companies that conduct business in highly competitive environments or offer undifferentiated products may find it difficult to raise their prices in response to increased costs. This is because, in the event that customers have easy access to alternative sources of supply, companies may find it necessary to absorb their increased costs rather than passing them on to consumers. Such retail sectors, commodity procurers, or manufacturing concerns offering standardized products are often faced with this dilemma. - Low Operating Margins
Inflation could affect businesses with narrow margins sooner than other businesses since an increase in costs of raw materials will cause them to suffer. Examples of industries for which inflation will have a significant impact if their pricing structures remain the same include airlines, fast food, logistics, and the transportation sector. - High Debt Levels (Interest Rate Sensitivity)
Higher interest rates due to inflation will increase the borrowing costs for organisations with significant amounts of debt; this will most severely impact businesses looking to expand through infrastructure investment, those who require borrowing in the real estate sector, and businesses in various sectors of manufacturing attempting to grow their business. - Dependence on Discretionary Spending
Consumers will likely prefer buying fewer of their non-essential items when reducing their available funds due to inflation. Businesses that depend on discretionary spends (such as those selling luxury items, luxury electronics, traveling, leisure and entertainment) may expect a reduction in their sales due to rising prices for many consumers.
By evaluating market data from various sectors, you'll begin to develop a better grasp of what different sectors of the economy do in response to inflation. Comparing sector performance against current inflation rate trends will provide a better idea of what true resilience is when it comes to your business.
Real-World Illustration: Inflation and Sector Resilience: Did FMCG Act as a Hedge?
When investors talk about stocks as an inflation hedge, the conversation often turns into a simple comparison, returns versus inflation percentages. But that comparison can be misleading. Inflation rarely needs to be beaten numerically to demonstrate hedging behaviour. A more practical perspective would be to consider whether some industries are able to maintain their position in the face of rising prices.
Analyzing the inflation trend in relation to the Nifty FMCG index over the last ten years provides a better insight into the performance of the sector during the fluctuating price conditions. During the period between 2014 and 2024, inflation in India remained largely moderate at around 3% to 7%. Although this does not seem too alarming, it still depicts a gradual increase in prices that the companies had to adapt to.
When the annual returns of the FMCG sector are placed alongside inflation trends, something interesting becomes clear. Higher inflation periods did not automatically lead to weaker performance for the sector. Returns moved up and down from year to year, as equity markets naturally do, but there was no clear pattern of sustained decline when inflation increased. Instead, the sector continued to deliver positive performance across several periods where price pressures were elevated.
This helps clarify what “hedging inflation” actually means in practice. A hedge is not about delivering returns that precisely track or exceed inflation every year. Rather, it is about resilience, the ability to maintain stability and avoid significant erosion in value even when the economic environment becomes more challenging.
FMCG companies are a good example in this context because of the nature of their business. They are involved in necessary consumption categories like food, home, and personal care products, where demand is less likely to be affected by economic conditions. When prices rise, FMCG firms require time to adjust their prices, alter the packaging size, or improve efficiency. Such steps may not be able to curb the fluctuations, but they are quite useful in maintaining stability.
It can be seen from the graph that although inflation was steady over time, the returns of FMCG companies did not deteriorate with increasing price pressures.
For investors, this is an important distinction. Inflation creates the context, but resilience is driven by business qualities: pricing power, sustainable demand, and cost management abilities. Stocks that have these qualities may not offer returns that are perfectly smooth, but they can help investors protect their wealth when inflation quietly reduces the value of money in the background.
Over time, changing inflation trends may also require periodic portfolio adjustments to maintain balance. Understand More through our article: What is Rebalancing? Why and When You Should Adjust Your Portfolio
So the takeaway isn’t that one sector magically “beats” inflation, but that certain business qualities matter more during rising price environments. The real challenge now is how investors can apply this understanding in practice.
Explore our Products
Research Framework

Emerging Titans
Combination of quantitative analysis, industry tailwinds, and management assessment - SPRINT investment philosophy

Tiny Titans
Heavy emphasis on scuttlebutt research, plant visits, and early on-ground signals
Conclusion: Investing Beyond Nominal Growth
Inflation never comes as a dramatic occurrence; it is a silent process that changes the value of money with time. The problem for investors, however, is not the sudden increase in prices but the gradual difference between nominal and actual progress. The key to understanding inflation, therefore, is not just observing the rising numbers but also considering whether savings and investments are actually protecting purchasing power.
“The stock market is designed to transfer money from the Active to the Patient.”- Warren Buffett
One thing that has been clear throughout this article, however, is that there is one thing that does not work well in protecting investors from inflation: there is no asset class that does it well. The key to protection, however, is not in the asset class but in understanding how different companies react to rising prices and changing economic conditions. Even then, however, not all companies will move in a straight line, as illustrated in the example.
Ultimately, outpacing inflation is less about forecasting prices and more about cultivating a mindset that prioritizes actual returns. If this has changed the way you think about inflation and investing, please leave a comment below with the word “Inflation”, share this with someone who still defines success solely by nominal returns, and answer me: When assessing an investment, do you take into account its performance relative to inflation?
FAQs
What is inflation, and why does it matter for investors?
+Inflation refers to a sustained increase in the general price level of goods and services over time. For investors, inflation matters because it reduces purchasing power, meaning that money must grow faster than rising prices to preserve real wealth.
What is the difference between nominal returns and real returns?
+Nominal returns are the raw percentage gains from an investment without considering inflation. Real returns adjust for inflation and show the actual increase (or decrease) in purchasing power after accounting for rising prices.
Why can savings accounts or fixed deposits lose value during inflation?
+Even if savings accounts or fixed deposits generate positive returns, they may still produce negative real returns if the interest earned is lower than the inflation rate. Over time, this means your money may buy less despite growing numerically.
Do stocks always protect against inflation?
+No. Stocks do not automatically act as perfect inflation hedges. However, certain companies or sectors with strong pricing power, stable demand, or resilient business models may adapt better during inflationary periods.
What makes a company more resilient during inflation?
+Businesses with pricing flexibility, essential products or services, healthy margins, manageable debt levels, and the ability to control costs are generally better positioned to navigate rising prices.

High growth stock specialist, Value Educator
Shashank Mahajan is an equity research professional with over 12 years of experience in identifying high-potential SME and micro-cap stocks at an early stage. He follows a rigorous scuttlebutt research–driven approach, combining on-ground insights with deep financial analysis. Shashank specializes in uncovering under-researched and under-owned companies with strong management quality and long-term growth potential. Through disciplined research and early identification, he focuses on spotting tomorrow’s market leaders before they enter the mainstream investor radar.

Glenmark: The USD 700 Mn Cancer Deal and Its Brands

Pharma Stocks in India 2026: Generics, APIs and CDMOs

Granules India: From Paracetamol to a 65% Gross Margin

Natco Pharma: After Revlimid, 29 Patent Challenges

Shilpa Medicare: Cancer APIs, Films and Biosimilars

Alembic Pharma: US Plants Pay Back, Margin Hits 22.2%
Explore our Products
Research Framework
Emerging Titans
Combination of quantitative analysis, industry tailwinds, and management assessment - SPRINT investment philosophy
Tiny Titans
Heavy emphasis on scuttlebutt research, plant visits, and early on-ground signals



Modern Warfare to Multibaggers
Key Trends. Strategic Shifts. Opportunities Ahead.
Today at 7:00 PM IST. Room opens 30 minutes before.
Don't Miss This Exclusive Webinar!
Join Value Educator to decode the key trends shaping India's defence sector and learn how to identify tomorrow's potential leaders in the space.
- In-depth research on India's defence sector
- Live Q&A session
- Actionable takeaways for long-term investors

 Orders
 Subscription
 Share with friends


Required Details
₹23999.00
(12 month subscription)
As per SEBI regulations, all users are mandated to complete the KYC that is validated for 1 year. Post payment, you will be redirected to the KYC screen


No comments yet. Be the first to comment!